
How family LLCs and partnerships support succession
Key takeaway
In Minnesota, for example, transferring an LLC interest gives the transferee distribution rights without automatically conferring management rights, while other states differ.
For a family considering a transfer, start with three questions: What rights will the recipient receive? What powers will the donor keep? How will the interest be valued?
Distribution rights and management rights are separate
In Minnesota, for example, a whole or partial transfer of an LLC's transferable interest gives the recipient the transferred distribution rights. Other states differ.
The transfer alone does not dissociate the member, dissolve the LLC or require winding up. It also does not confer management rights or ordinary access to company records.
During dissolution and winding up, the transferee has a right to an accounting only from dissolution. A deceased member's representative may also exercise current member information rights for settling the estate.
The LLC need not give effect to the transferee's rights until it receives notice of the transfer. A transfer violating an operating agreement restriction is ineffective as to someone who knew of that restriction when the transfer occurred.
Before discussing a transfer with your advisers, identify the intended recipient, the distribution rights involved and any admission or transfer provisions in the agreement.
Who makes the decisions
In Minnesota, for example, an LLC defaults to member management unless its operating agreement specifies manager or board management, including equivalent wording. Specified nonprofit LLCs are excluded from this default, and other states differ.
For a manager managed LLC, managers generally decide company activities exclusively and have equal management rights. A majority of managers may decide ordinary course disagreements.
Under the statutory defaults, all members must consent to disposing of substantially all company property outside ordinary activities, mergers, conversions, domestications, other extraordinary acts and operating agreement amendments.
The operating agreement governs subject to statutory limits. Review its terms before relying on these defaults.
In Minnesota, for example, each general partner in a limited partnership has equal management rights. Except as expressly provided by the governing statute, the general partner, or a majority of general partners, may decide activities exclusively. Other states differ.
The statutory rules require every partner's consent to amend the partnership agreement or dispose of substantially all property outside usual and regular activities.
Every partner's consent is also required to amend the certificate to add limited liability limited partnership status or, subject to the statutory conversion provisions, delete that status. Review the agreement before applying these rules.
Retained powers need two separate tax reviews
Gift completion depends on whether the donor has relinquished dominion and control over disposition. A retained power to revest beneficial title in the donor makes the gift incomplete.
A power to name beneficiaries or change their respective interests makes the gift incomplete to that extent, unless it is a fiduciary power limited by a fixed or ascertainable standard.
Powers exercisable jointly with someone who lacks a substantial adverse interest count as the donor's powers. Examine the scope of every reserved power.
Estate inclusion is a separate question. Under the federal retained interest rule, transferred property is included in the gross estate if the transferor retains possession, enjoyment, income or a right to designate who possesses or enjoys it.
The retained right may be exercisable alone or with another person. It must last for life, for a period not ascertainable without reference to death, or for a period that does not actually end before death.
A bona fide sale for adequate and full consideration is excepted. Ask your advisers to review both gift completion and estate inclusion when evaluating retained powers.
A transfer restriction does not automatically establish tax value
For transfer tax valuation, an option or agreement to acquire or use property below fair market value, or a restriction on sale or use, is disregarded unless it meets all three federal tests.
- It is a bona fide business arrangement.
- It is not a device to transfer property to family members for less than full and adequate consideration.
- Its terms are comparable to similar arrangements made at arm's length.
A price in a buyout agreement therefore does not automatically set estate tax value. Bring both the agreement and the proposed valuation to the same discussion with your advisers.
Two related terms
Fair market value is the price a willing buyer and willing seller would agree on, neither under compulsion and both knowing the relevant facts. Estate tax valuation does not use a forced sale price, and alternate valuation may apply if elected.
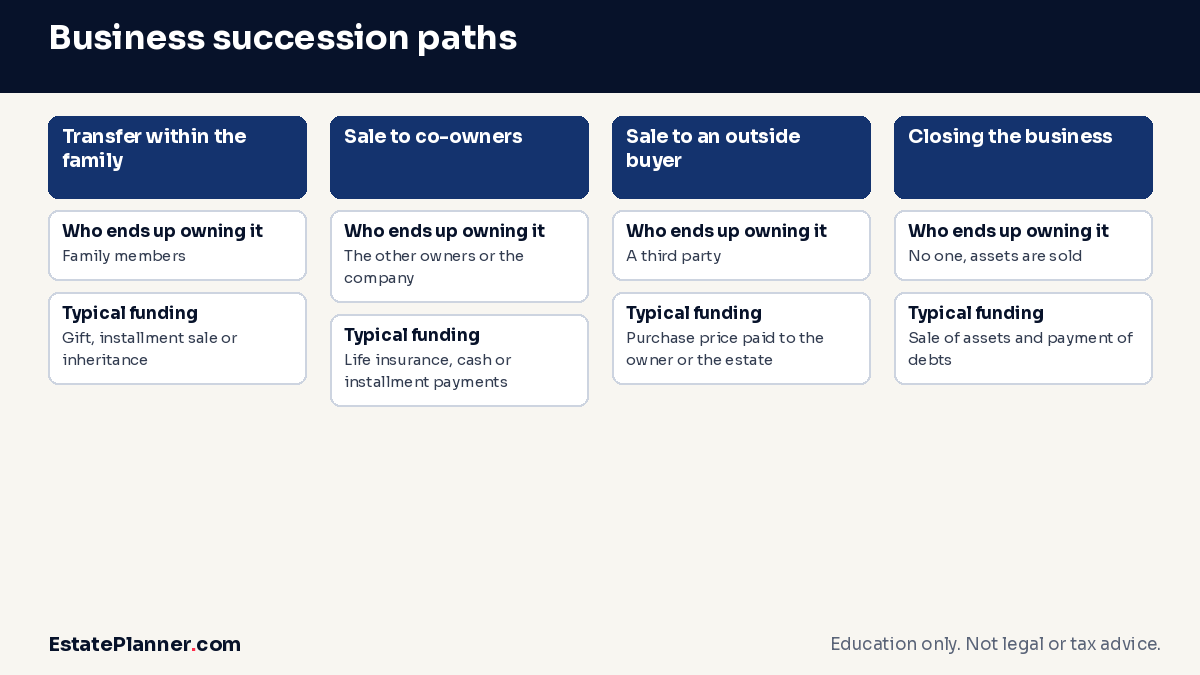
Cross purchase agreement describes an arrangement in which owners agree to buy each other's shares at death and purchase life insurance on each other to fund it. The owners pay the premiums, and proceeds go to the surviving owner rather than the company.
A perspective on working across specialties
When preparing the family discussion, invite your legal, tax and valuation advisers to consider the same proposed transfer. This speaker's reflection offers a useful reminder about professional silos.
"You know, I was just kind of like most of us in the financial service industry, we're kind of in our silos."
Common questions
When does a partnership tax year close for a departing partner?
The partnership's tax year closes with respect to a partner whose entire interest terminates, including by death, liquidation or otherwise. A partial disposition does not close the tax year for that partner.
Put the termination date and the extent of the interest ending on the agenda for your tax adviser.
Does keeping control over timing always make a gift incomplete?
No. Retaining only a power to change the manner or time of enjoyment does not itself make a gift incomplete.
For the broader review of reserved powers and estate inclusion, see Retained powers need two separate tax reviews.
Sources
- Minnesota Statutes §322C.0407: LLC management rules and member consent requirements.
- Minnesota Statutes §322C.0110: operating agreement authority and statutory limits.
- Minnesota Statutes §322C.0502: transferable interests, notice and restrictions.
- Minnesota Statutes §322C.0504: rights of a deceased member's representative.
- Minnesota Statutes §321.0406: general partner management and partner consent.
- Treasury Regulation §25.2511-2: gift completion and reserved powers.
- Internal Revenue Code §2036: transfers with retained interests.
- Internal Revenue Code §2703: options, agreements and restrictions in transfer tax valuation.
- Treasury Regulation §20.2031-1: estate tax fair market value.
- Internal Revenue Code §706: closing the tax year with respect to a partner.
- Connelly v. United States: description of a cross purchase arrangement.